Analyst: Jeremy Mikael
Nickel Industries (NCCL) recorded strong growth in FY24, with revenues reaching IDR26.96tn (+13% y-y), slightly above the estimate. Net profit also rose 13.5% y-y to IDR6.38tn, outperforming consensus expectations despite quarterly earnings weakening at 4Q24.
📉 4Q24 Revenue Down 13% Q-Q
What about NCCKL's revenue performance , NCCL's quarterly performance fell to IDR 6.58tn (-13% q-q; +0.4% y-y) due to the decline in sales volume of limonite to 4.5 million tons (-10.6% q-q) and less ferronickel delivery (29.17k tons, -12.1% q-q).
🔥 Smelter & HPPAL supported performance
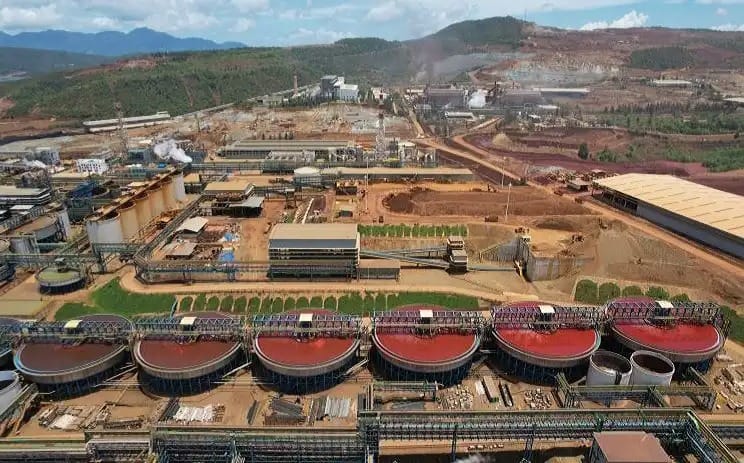
RKEF smelter recorded production of 126.34K tons (+25.2% y-y), while sales of limonite jumped 60.7% y-y to 14.6 million wmt, driven by fully operational ONC hpal. MHP's cash margin also strengthened to USD8,283/ton (+4% Q-Q; +11.8% y-y) thanks to the efficiency of the HPAL smelter.
💰 Cheap valuation, buy with tp IDR1200!
Then how is NCCKL in the viewpoint of valuation? NCKL is currently valuation at 5.5x P/E, well below the industry average, we maintain the BUY recommendation with TP IDR1200, equivalent to 10x P/E FY25E.
Full pdf: nckl0325
Disclaimer on:
Buying and selling decisions are personal responsibility
Regards
Investment Specialist